Stories
Gold Prices Plunge 23 Percent: What It Means For Your Gold Loan LTV
- •International and domestic gold prices have dropped nearly 23 percent from their yearly peaks, impacting the value of pledged jewellery.
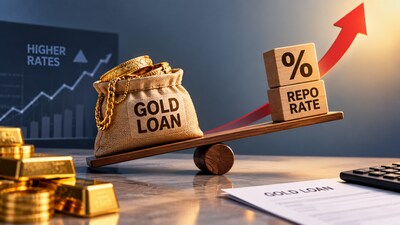
- •A falling gold price increases the loan-to-value (LTV) ratio, potentially triggering margin calls from lenders who may demand additional collateral or partial repayment.
- •Bullet repayment loans carry higher LTV risks since the principal remains unchanged while collateral value declines, unlike EMI loans which have a natural cushion.
- •Gold price fluctuations do not automatically alter scheduled EMIs or repayment obligations, as borrowers must still repay principal and interest as agreed.
Key Questions Answered
When gold prices drop sharply, the market value of the pledged jewellery decreases while the outstanding loan amount remains unchanged. This raises the loan-to-value (LTV) ratio, potentially pushing it beyond acceptable thresholds and leading lenders to ask borrowers for additional collateral or partial repayment.
In bullet repayment loans, borrowers pay the principal only at maturity, meaning the outstanding debt does not reduce over time. If gold prices fall during the tenure, the collateral value drops while the debt stays the same, causing the LTV ratio to spike rapidly and increasing the risk of margin calls.
No, fluctuations in gold prices do not automatically change a borrower's EMI or repayment schedule. Borrowers remain legally obligated to repay the principal and interest as originally agreed under their loan terms, regardless of whether gold prices rise or fall.