Stories
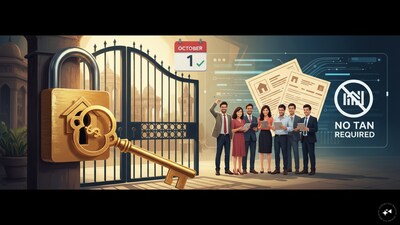
New TDS Rules for Property Buyers Dealing with NRI Sellers Effective October 1
- •The CBDT has notified new TDS reporting requirements for resident individuals and HUFs buying immovable property from non-resident sellers, effective October 1.
- •Resident individuals and HUFs will no longer require a Tax Deduction Account Number (TAN) for these transactions, and the TDS payment timeline extends to 30 days.
- •Form 26QB has been amended with a new Schedule E to capture detailed information about property transactions involving non-resident sellers, including buyer and seller PAN, property details, and capital gains nature.
- •Buyers must provide extensive details for non-resident sellers, including PAN (if available), name, status, contact information, and tax residency details, even if PAN is not available.
- •Each joint buyer will have separate reporting requirements, and the changes primarily amend TDS reporting and documentation, not property ownership rules.
Key Questions Answered
Starting October 1, resident individuals and Hindu Undivided Families (HUFs) buying property from non-resident sellers no longer need a Tax Deduction Account Number (TAN). The new framework brings these transactions into the prescribed TDS challan-cum-statement mechanism and extends the TDS payment timeline to 30 days from the end of the relevant month.
Buyers must report the property address, property type, and details for all buyers and non-resident sellers, including PAN, names, and payment proportions. For sellers, buyers must also provide contact numbers, email IDs, foreign addresses, tax residency certificate numbers, and tax identification numbers.
If an NRI seller lacks a PAN, the buyer must provide the seller's tax identification number from their country of residence. If a tax ID is absent, a unique number utilized by the foreign government to identify the seller must be furnished to ensure tax is not deducted at a higher rate.