Stories
TDS Compliance Eased for Property Bought from Non-Residents: No TAN Required from Oct 1
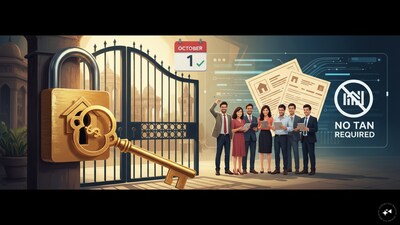
- •The CBDT has amended Income-tax Rules, 2026, simplifying TDS compliance for resident individuals and HUFs buying immovable property from non-residents, effective October 1, 2026.
- •The most significant change is the removal of the requirement for buyers to obtain a separate TAN; compliance can now be done via a PAN-based challan.
- •Form 141 (challan-cum-statement) has been expanded with a new Schedule E to cover TDS deductions under Section 393(2), requiring comprehensive details of the property, buyers, and non-resident sellers.
- •Buyers must provide detailed information about non-resident sellers, including overseas address, Tax Residency Certificate (TRC) number, and Tax Identification Number (TIN), even if the seller has a PAN.
- •While compliance is simpler, buyers still need to correctly deduct and report TDS, including surcharge and cess, and gather necessary seller information before the transaction.
Key Questions Answered
The Central Board of Direct Taxes amended the Income-tax Rules to simplify TDS compliance for resident individuals and HUFs purchasing immovable property from non-residents, effective October 1, 2026. The most significant relief is the removal of the requirement to obtain a separate TAN, allowing buyers to comply through a PAN-based challan.
Resident individuals and HUFs no longer need to obtain a separate Tax Deduction Account Number for what is often a one-time property transaction with a non-resident seller. Instead, buyers can use a PAN-based challan-cum-statement under the newly expanded Form 141 and Schedule E.
Buyers must provide comprehensive details of the non-resident seller, including their PAN where available, contact number, email ID, overseas address, Tax Residency Certificate number, and foreign Tax Identification Number. The form also captures transaction-specific information such as the agreement date, stamp duty value, sale consideration, and TDS calculations.