Stories
IRDAI Targets Mis-Selling: Agents' Records Public, Accountability Tightened
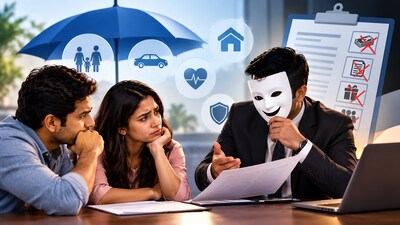
- •IRDAI proposes tighter accountability for insurance agents to protect buyers from mis-selling, identifying 12 problematic practices.
- •The regulator plans to make individual salespersons' mis-selling records publicly available to help customers make informed decisions.
- •Flagged practices include selling regular-premium policies as single-premium, not explaining surrender values, and selling to non-working age customers.
- •Other concerns include selling ULIPs to risk-averse clients without explaining charges, promising assured returns falsely, and misrepresenting insurance as deposits.
- •The proposal also includes commission claw-back by insurers for mis-sold policies, creating a clearer accountability trail for policyholders.
Key Questions Answered
The IRDAI consultation paper identified 12 problematic selling practices, such as selling regular-premium policies as single-premium products, marketing life insurance to non-working or dependent customers without steady income, selling ULIPs to risk-averse buyers without explaining risks, and falsely promising assured returns or higher bank deposit equivalents.
The regulator proposes tagging the functional identity of the salesperson, agent, or point-of-sale person to the sold policy and making their mis-selling records public. Additionally, the framework introduces 'commission claw-back' allowing insurers to recover previously paid commissions if a policy is later found to be mis-sold.
The proposed distribution reforms aim to fix sales accountability, protect buyers from unfair business practices, and empower prospective customers to make informed decisions by exposing the mis-selling histories of salespersons. Furthermore, the regulator is looking to curb high distribution costs and address commission-led practices that harm policyholders.