Stories
India's Credit Revolution: Connecting Capital with Borrowers Through Tech and P2P Lending
- •India's next growth phase requires increased credit for individuals and small businesses, not just large corporations.
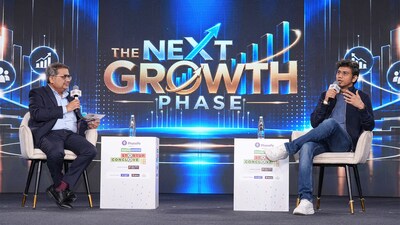
- •Bhavin Patel, Co-founder and CEO of Vartis Platforms & LenDenClub, highlights technology, P2P lending, and specialized credit platforms as key to connecting capital with diverse borrowers.
- •Digital platforms can efficiently assess and process smaller loans, complementing traditional banks and NBFCs by serving unique credit needs.
- •P2P lending allows individuals to participate directly in the credit economy, diversifying portfolios and financing growth, though it involves credit risk.
- •Strong regulation, advanced technology, and smarter risk management are crucial for building a robust credit market where capital reaches more people and more individuals can participate as lenders.
Key Questions Answered
Regulated P2P lending platforms act as intermediaries connecting individual lenders directly with borrowers looking for credit, allowing participants to diversify their portfolios while bearing the underlying credit risk. This setup means repayment is not assured, and lenders can lose money if a borrower defaults.
Digital onboarding, data analysis, automated checks, and artificial intelligence help platforms identify patterns across large numbers of borrowers faster. This allows companies like LenDenClub to process smaller loans efficiently and make informed credit decisions at scale without relying solely on manual work.
India created a formal regulatory framework for P2P lending in 2017, and this framework has continued to evolve over time to provide clear boundaries for responsible participation.