Stories
ULIPs vs. Traditional Life Insurance: Which Suits Your Financial Goals Best?
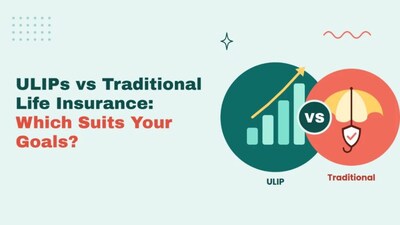
- •ULIPs combine life insurance with market-linked investments, allowing policyholders to choose funds (equity, debt, balanced) and bear investment risk.
- •Traditional life insurance offers life cover with savings benefits, potentially including guaranteed benefits or bonuses, with less direct market exposure.
- •Key differences include investment risk (policyholder for ULIPs, product-dependent for traditional), returns (fund performance vs. guaranteed/bonuses), and flexibility.
- •Both are long-term products; ULIPs often have a lock-in period, while traditional policies may have surrender conditions affecting early exit value.
- •Consider charges, tax implications, liquidity, and your comfort with investment risk before choosing, as features and costs vary significantly.
Key Questions Answered
A Unit Linked Insurance Plan (ULIP) combines life cover with market-linked investments where the policyholder bears the investment risk, whereas traditional life insurance focuses on guaranteed or declared benefits through savings-oriented planning. Traditional plans usually feature a predefined benefit structure without direct fund selection by the policyholder.
In a ULIP, the investment risk is typically borne by the policyholder who selects from equity, debt, or balanced funds that fluctuate with market performance. In contrast, traditional life insurance products provide more predictable benefits through guaranteed amounts or bonuses declared by the insurer, making them less directly tied to market movements.
Both plans are designed for the long term and feature conditions such as surrender rules, partial withdrawals, and minimum holding periods. ULIPs include a strict lock-in period and various charges like premium allocation, fund management, and mortality fees, while traditional policies may impose surrender penalties for early exits where payouts fall below total premiums paid.