Stories
What to Review at Car Insurance Renewal When Driving Less

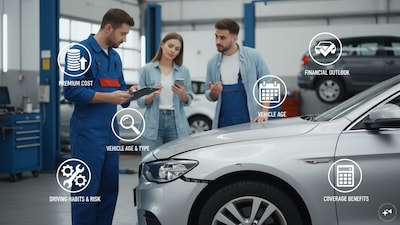
- •Evaluate how your driving habits and vehicle usage have changed over the past year before renewing your policy.
- •Explore usage-based insurance options like Pay As You Drive if your annual mileage has dropped significantly.
- •Maintain adequate coverage levels regardless of lower usage to protect against theft, fire, and weather damage.
- •Review your policy add-ons carefully based on the car's current age, condition, and parking location.
- •Ensure your Insured Declared Value reflects the vehicle's market depreciation rather than your lower mileage.
Key Questions Answered
Pay-As-You-Drive insurance links part of the own-damage premium to how much the vehicle is actually driven, allowing low-usage drivers to choose an annual kilometre slab and pay lower premiums. Insurers measure distance using client-provided odometer readings or telematics and mobile technology, while mandatory third-party insurance remains regulated and unchanged.
No, your car's Insured Declared Value (IDV) should not be reduced simply because you drove fewer kilometres. IDV relates to the insured value of the vehicle and normally changes as the car ages and depreciates. Low annual running alone should not justify choosing an unusually low IDV.
Yes, using your car less does not remove the need for active insurance. Even when parked for long periods, a vehicle remains exposed to theft, fire, weather damage, or accidental impact. Timely renewal prevents coverage breaks and keeps policy benefits active.