Stories
Is Zero Depreciation Car Insurance Worth It? 5 Key Things to Consider
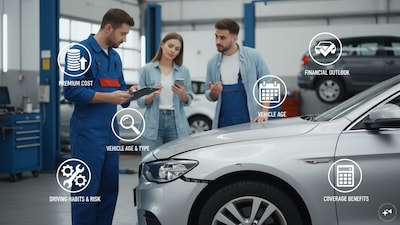
- •Standard comprehensive car insurance may deduct depreciation costs when replacing damaged parts, leaving you to pay the difference.
- •Zero depreciation cover is an add-on that removes this depreciation deduction, significantly lowering your out-of-pocket repair bills, especially for newer cars.
- •Choosing this add-on increases your overall insurance premium, so you must evaluate if the extra cost is justified by your car's age and value.
- •Insurers often limit the number of claims eligible for zero depreciation benefits and may restrict the add-on for older vehicles.
- •Zero depreciation does not mean zero payment; you will still need to handle deductibles, exclusions, and mechanical issues or normal wear and tear.
Key Questions Answered
Zero depreciation cover is an add-on to comprehensive car insurance that removes depreciation deductions on eligible parts when settling a claim, reducing out-of-pocket repair costs for car owners. However, it does not mean repairs are entirely free, as policyholders still need to handle deductibles and normal wear and tear remains excluded.
No, purchasing zero depreciation cover does not automatically mean you can file an unlimited number of claims. Insurers frequently enforce specific limits on how many times the zero depreciation benefit can be utilized annually, making it vital to review these restrictions before purchasing.
Older cars may not qualify, as insurance providers typically enforce a maximum vehicle age limit beyond which zero depreciation add-ons are no longer offered. Since the coverage is primarily designed for newer vehicles where replacement parts are very expensive, owners of older cars must carefully weigh the extra premium against realistic savings.