Stories
Tax Relief: Sold Ancestral Land, Bought Properties, Then Turned Tables on Income Tax Department!
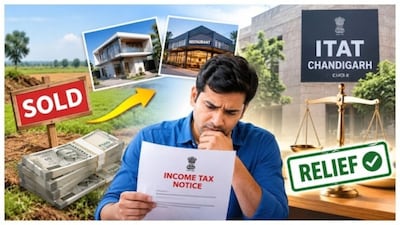
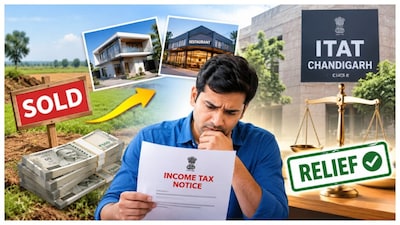
- •Tiwari from Panchkula sold ancestral agricultural land worth 8 crore rupees and bought two new properties.
- •He claimed exemption on long-term capital gains tax under sections 54F and 54B, but the Income Tax Department rejected his claim.
- •The IT Department initially considered Tiwari's Dhakoli property as residential, disallowing exemption under 54F.
- •An investigation by the Income Tax Appellate Tribunal (ITAT) revealed the Dhakoli property was commercial, leading to a 2.64 crore exemption under 54F.
- •The ITAT also cleared Tiwari's claim under 54B, confirming that urban land used for agriculture qualifies for exemption.
Key Questions Answered
Tiwari approached the Chandigarh ITAT, which ordered an investigation that proved his Dhakoli property was located in a commercial area and used for commercial purposes. The Tribunal ruled that owning a commercial property does not violate Section 54F's condition against possessing more than one residential house, thereby removing the tax disallowance.
The Income Tax Department questioned Tiwari's purchase of urban land worth 80 lakh and 45 lakh. However, the ITAT's investigation revealed that the properties were officially designated and used for agricultural purposes, clarifying that urban location alone does not disqualify land from Section 54B exemptions.
Tiwari reported a long-term capital gain of approximately 7.73 crore rupees after selling his share of agricultural land for 8 crore rupees on September 18, 2017. He sought exemptions of approximately 2.64 crore rupees under section 54F and 3.73 crore rupees under section 54B.