Stories
Why One Bank is No Longer Enough for Modern Indian Consumers
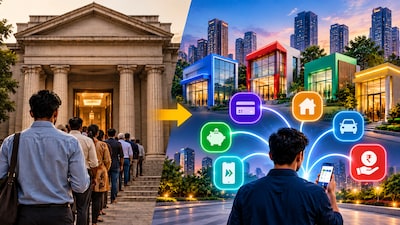
- •The traditional single-bank customer relationship model is rapidly declining as digital banking and fintech platforms offer consumers a wide array of specialized financial products.
- •Consumers now mix and match financial services, using different institutions for salary accounts, credit cards tailored to specific spending habits, home loans, and high-yield deposits.
- •Regulatory support for digital KYC, account aggregators, and data sharing has enabled seamless interoperability across the financial ecosystem.
- •Banks are increasingly forming co-branded partnerships with major brands like Amazon, Flipkart, and Tata Neu to attract and acquire new customers.
- •The rise of multiple banking relationships and fintech platforms has turned traditional brand loyalty into smart, choice-driven consumer behavior.
Key Questions Answered
The shift away from the single-bank model was driven by digital choices, where customers can access banking products using smartphones, digital KYC, and fintech marketplaces that compare interest rates. This change originally began in the credit card market as customers started maintaining multiple cards for specific benefits like rewards, travel, and online shopping.
The government and regulators promote interoperability and sharing of data through digital KYC, credit bureaus, account aggregators, and GST data, allowing financial products to be accessed from anywhere. Platforms and apps also make the application journey easier and provide specialized services across different lenders.
Banks have launched co-brand partnerships with major platforms to attract customers, such as ICICI Bank and Amazon, Axis Bank and Flipkart, and Tata Neu and HDFC Bank. These partnerships allow lenders to compete for specific spending benefits and offer higher-value rewards or lower interest rates.