Stories
Switching Health Insurers? Your Waiting Period Might Not Reset!
M
Moneycontrol•22-09-2026, 23:56
Switching Health Insurers? Your Waiting Period Might Not Reset!
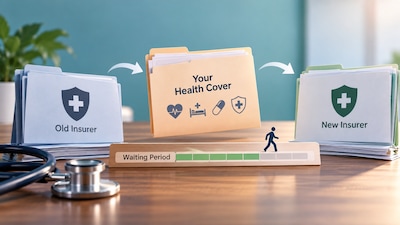
- •Portability rules allow credit for waiting periods on pre-existing diseases and time-bound exclusions to transfer to a new insurer, avoiding a complete reset.
- •Continuity credit can reduce remaining waiting periods, but a break in coverage can affect these benefits.
- •A higher sum insured with a new policy may mean the additional amount is subject to fresh waiting periods, while the original sum insured retains continuity benefits.
- •Not all benefits transfer; no-claim bonuses, add-ons, and other policy features may differ with the new insurer.
- •Apply for portability 30-45 days before renewal, provide accurate information, and keep the old policy active until the switch is complete.
Key Questions Answered
Not necessarily. Under IRDAI portability rules, the credit earned for waiting periods on pre-existing diseases and time-bound exclusions can move to your new insurer, subject to applicable conditions and continuous coverage.
The continuity benefit generally applies only to the cover carried forward from your old policy. If you increase your sum insured, the additional coverage amount can be subject to fresh waiting-period requirements under the new policy.
Portability must generally be exercised at renewal. Industry guidance and insurers commonly advise starting the process around 30 to 45 days before your existing policy expires, while keeping your current policy active until the switch is complete.