Stories
Super Top-Up vs. Bigger Policy: Which Offers Better Health Cover for Rs. 50 Lakh?
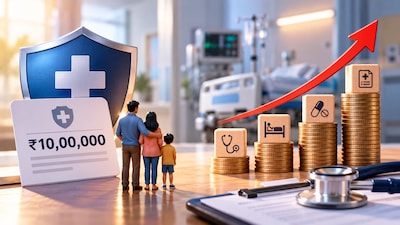
- •Increasing health protection from Rs. 10 lakh to Rs. 50 lakh can be done by raising the base cover or adding a super top-up policy.
- •A super top-up is generally cheaper but only activates after a chosen deductible is crossed, unlike a bigger base policy which covers from the first expense.
- •Super top-ups apply the deductible on an aggregate basis for the policy year, making them useful for multiple hospitalizations within the same year.
- •A higher base policy simplifies claims as there's no separate deductible hurdle, but it comes with a substantially higher premium.
- •Policyholders must ensure their base cover handles common hospital bills before using a super top-up for protection against much larger, less frequent expenses.
Key Questions Answered
A larger base policy covers medical expenses from the first rupee of an admissible claim. In contrast, a super top-up policy only kicks in after a chosen deductible threshold is crossed during the policy year.
A super top-up can cover cumulative expenses once the total admissible claims cross the annual deductible limit. For instance, if you have two separate claims of Rs. 6 lakh each totaling Rs. 12 lakh with a Rs. 10 lakh deductible, the super top-up can respond to the amount exceeding the Rs. 10 lakh threshold subject to policy terms.
If your base policy is small, such as Rs. 5 lakh, but your super top-up has a Rs. 10 lakh deductible, you may have to pay out of pocket if claims fail to meet the higher deductible threshold under the super top-up's terms.