Stories
Super Senior Citizens: Are You Exempt from ITR Filing if Bank Deducts Tax?
- •Senior citizens aged 75 or above may be exempt from filing ITR under specific conditions, even if the bank deducts tax on interest income.
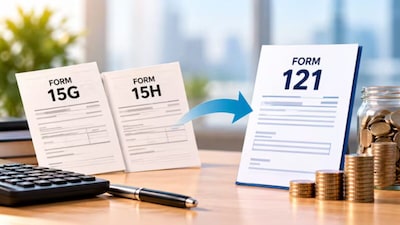
- •The exemption applies if the senior citizen is a resident, has only pension income and interest from the same specified bank, and submits Form No. 125.
- •The specified bank is responsible for calculating and deducting the tax liability, after which the senior citizen is not required to file an ITR.
- •If interest income is from a different bank or there are other income sources, the exemption does not apply, and normal ITR-filing provisions must be followed.
- •Being a super senior citizen alone does not guarantee ITR exemption; specific legal conditions must be met.
Key Questions Answered
Not automatically. While resident senior citizens aged 75 or above can be exempt from filing an ITR under specific provisions, the mere fact that a bank has deducted tax does not grant a blanket exemption. The exemption only applies if strict conditions regarding income sources and document submission are met.
The individual must be a resident aged 75 or older, with income restricted strictly to pension and interest received from the same specified bank managing that pension account. Additionally, they must submit the prescribed Form No. 125 declaration to that specific bank so it can compute and deduct the correct tax liability.
If a senior citizen receives interest income from a bank different from their pension-disbursing bank, or holds any other source of income, the special ITR exemption provision does not apply. In such scenarios, normal income tax return filing rules must be followed.