Stories
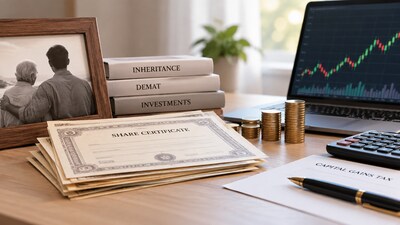
Inherited Shares: Unraveling Capital Gains Tax on Sale
- •For inherited capital assets, the taxpayer can use the original owner's cost basis; if acquired before April 1, 2001, the fair market value as of April 1, 2001, can be used for long-term capital gains.
- •For inherited listed shares or equity-oriented schemes, grandfathering provisions apply, using January 31, 2018, as the reference date if acquired by the original owner before February 1, 2018.
- •The cost of acquisition for equity shares is the higher of the actual cost or the Fair Market Value on January 31, 2018; for listed shares, it's the highest stock exchange price on that date.
- •Grandfathering provisions apply even if shares were inherited after January 31, 2018, provided the original owner acquired them before February 1, 2018, allowing the use of the closing price on that date as cost.
- •Indexation benefit is not available for these capital assets; a flat tax rate of 12.50 percent applies to long-term capital gains exceeding Rs. 1.25 lakh from listed shares and equity-oriented schemes.
Key Questions Answered
Yes, the grandfathering provisions will apply even if the shares were inherited after the January 31, 2018 cut-off date, provided the original owner acquired them before February 1, 2018. You can use the highest stock exchange price on January 31, 2018, as your cost of acquisition.
For inherited capital assets, the taxpayer may use the original owner's cost basis, or the fair market value as on April 1, 2001, if acquired before that date. For listed shares acquired prior to February 1, 2018, the cost is the higher of the actual cost or the highest stock exchange price on January 31, 2018.
No, the benefit of indexation is not available for these capital assets. You are required to pay tax at a flat rate of 12.50 percent on long-term capital gains exceeding Rs. 1.25 lakh for listed shares and equity-oriented units taken together.