Stories
Five Smart Strategies to Keep Credit Card Debt Under Control
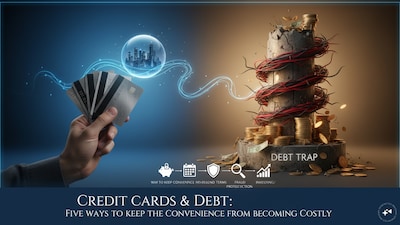
- •Always pay the full amount due by the deadline to avoid losing the interest-free period and incurring steep charges.
- •Keep your credit utilization below 30 percent to protect your credit score and avoid heavy dependence on credit.
- •Never treat the minimum amount due as your monthly budget, as interest rates on card balances can reach up to 36 percent annually.
- •Avoid applying for multiple cards too frequently and manage your credit lines carefully to prevent overspending.
- •Treat rewards and cashback as a bonus rather than an excuse to make unplanned purchases that lead to debt.
Key Questions Answered
Paying only the minimum amount due prevents the account from immediately becoming overdue, but it fails to clear the outstanding balance and causes you to lose the interest-free period. According to RBI guidelines, interest is then charged on the outstanding amount from the original transaction date, and the remaining balance rolls forward with high interest that can substantially increase your costs.
CIBIL notes that a high credit utilisation ratio indicates a greater dependence on credit, and utilizing more than 30 percent of your available limit can begin to negatively impact your credit scores. A large credit limit does not mean extra income, so relying too heavily on it signals financial risk.
Having multiple cards can make it easier to overspend and harder to keep track of payment due dates. Furthermore, CIBIL highlights that applying for new credit too frequently within a short period can negatively affect your credit score.