Stories
RBI Finalizes Basel III Market Risk Capital Rules for Banks, Effective 2027
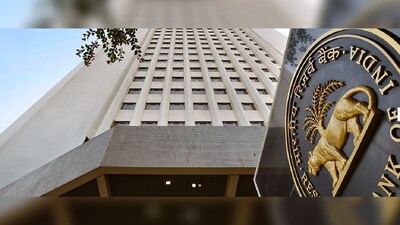
- •The Reserve Bank of India (RBI) issued final directions for minimum capital requirements for market risk under Basel III for commercial banks, effective April 1, 2027.
- •The guidelines adopt the Simplified Standardised Approach (SSA) for computing capital requirements, covering interest-rate, equity, and foreign-exchange risks.
- •The RBI clarified the boundary between banking and trading books, stating the trading book includes all 'Held for Trading' instruments for capital adequacy.
- •Banks cannot reclassify trading book instruments to the banking book for lower capital requirements; any such reclassification requires maintaining the capital difference.
- •Banks must meet market-risk capital requirements continuously at the close of each business day and can exclude certain structural foreign currency investments from Net Open Position (NOP) calculation under specific conditions.
Key Questions Answered
The Reserve Bank of India issued final directions for the minimum capital requirement for market risk under Basel III, proposing the adoption of the Simplified Standardised Approach for computing risk-weighted assets across interest-rate, equity, and foreign-exchange risk classes, effective April 1, 2027.
The trading book must include all instruments classified as 'Held for Trading', and banks cannot misclassify instruments into the banking book to lower capital requirements. If they do classify such instruments, they must calculate total capital requirements before and after and maintain the difference.
Banks have the option to exclude certain structural foreign currency investments from the Net Open Position on a case-by-case basis, provided the exclusion lasts for at least six months and the exemption is recalculated quarterly.